Posts

Caribbean Debt Tops US$91.7 Billion Across 10 Countries

Caribbean Debt Tops US$91.7 Billion Across 10 CountriesCaribbean Debt Tops US$91.7 Billion Across 10 Countries

By News Americas Now Business Editor

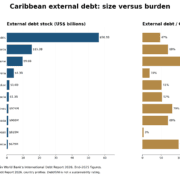
News Americas Now, MIAMI, FL, Fri. Nov. 20, 2026: Ever wondered how Caribbean debt stacks up by country? Ten Caribbean countries profiled in the World Bank’s International Debt Report 2026 owed a combined US$91.7 billion in external debt at the end of 2025 – but the countries with the largest debt loads are not necessarily the ones under the greatest repayment pressure.

The Dominican Republic dominates the ranking, owing US$56.3 billion, followed by Jamaica at US$15.3 billion and Suriname at US$9.6 billion. Guyana ranked fourth at US$4.3 billion, while Belize owed US$1.6 billion per an analysis by Invest Caribbean.

The remaining five were St. Lucia at US$1.3 billion; St. Vincent and the Grenadines at US$974.4 million; Grenada at US$905.8 million; Haiti at US$827.5 million; and Dominica at US$678.6 million.

The US$91.7 billion figure is a News Americas calculation based on the ten country profiles. It is not the total external debt of the entire Caribbean, since several countries — including Antigua and Barbuda, The Bahamas, Barbados, St. Kitts and Nevis and Trinidad and Tobago — are not individually profiled in the report. Cuba and non-sovereign Caribbean territories are also absent.

Who Owes The Most

Caribbean Debt Tops US$91.7 Billion Across 10 Countries

Ranked by total external debt stock, the ten countries are:

  1. Dominican Republic — US$56.3 billion
  2. Jamaica — US$15.3 billion
  3. Suriname — US$9.6 billion
  4. Guyana — US$4.3 billion
  5. Belize — US$1.6 billion
  6. St. Lucia — US$1.3 billion
  7. St. Vincent and the Grenadines — US$974.4 million
  8. Grenada — US$905.8 million
  9. Haiti — US$827.5 million
  10. Dominica — US$678.6 million.

But the ranking by size tells only part of the story. A country can owe less in absolute dollars while carrying a much heavier burden relative to the size of its economy or its ability to service that debt.

Jamaica And Suriname Face The Heaviest Repayment Pressure

Jamaica ranked second in total external debt, but its debt-service-to-exports ratio reached 54 percent, the highest of the ten countries profiled. Suriname followed at 44 percent, despite ranking third by total debt stock.

That ratio compares annual principal and interest payments with earnings from exports of goods, services and primary income. It is not a measure of how much of each export dollar is literally used to pay debt, but it provides a useful gauge of external repayment pressure.

Suriname also stood out for the sharpest rise in debt among the ten. Its external debt increased 37.2 percent to about US$9.6 billion, while its external debt-to-GNI ratio reached 228 percent. Jamaica’s debt stock, by contrast, rose only 1.8 percent, but its repayment burden remained high. Its debt-service-to-GNI ratio reached 18 percent.

Guyana Shows The Opposite Pattern

Guyana provides a sharp contrast. Its external debt increased 16.3 percent to US$4.3 billion, yet its debt-service-to-exports ratio was only 3 percent, and debt service relative to GNI was also 3 percent. Its external debt-to-GNI ratio stood at 19 percent. That means Guyana’s debt stock was rising, but the burden indicators in the World Bank profile remained among the lowest in the group.

Who Holds The Debt?

The data also reveal major differences in who Caribbean governments owe. The Dominican Republic, Jamaica and Suriname rely heavily on private creditors such as bondholders and commercial banks.

Private creditors hold about 77 percent of the Dominican Republic’s public and publicly guaranteed external debt, about 52 percent of Jamaica’s and about 42 percent of Suriname’s. By contrast, multilateral lenders dominate in several smaller Caribbean states. They hold most of the public external debt in Dominica, Haiti, St. Vincent and the Grenadines and Guyana.

Among the major named creditors are the Inter-American Development Bank, Caribbean Development Bank and World Bank’s International Development Association. The report also shows China as the largest named bilateral creditor to Guyana, Suriname and Jamaica, while Venezuela continues to appear on the balance sheets of Belize, Grenada and Haiti.

Smaller Countries Can Still Carry Heavy Debt Burdens

Debt size alone can also obscure risk among smaller economies. Dominica ranked last in the ten-country list by total external debt, at US$678.6 million, but that debt was equivalent to 96 percent of GNI.

St. Vincent and the Grenadines had external debt equal to 79 percent of GNI, while Grenada and Jamaica were each at 68 percent. Suriname remained the clear outlier at 228 percent.

Haiti’s Debt Fell

Haiti was the only one of the ten countries whose external debt declined in 2025. Its debt fell 12.7 percent to US$827.5 million, well below its 2015 level of US$2.24 billion. However, the World Bank profile does not explain the decline, and a lower debt stock should not automatically be interpreted as a sign of economic strength.

Debt Size Is Not The Same As Debt Stress

The clearest takeaway from the World Bank data is that headline debt numbers do not tell the full story. The Dominican Republic owes the most by far, but Jamaica and Suriname face heavier repayment pressure relative to export earnings.

Guyana’s debt is rising quickly, but its burden ratios remain comparatively low. And some of the smallest economies carry debt that is large relative to their national income. The numbers show that when it comes to Caribbean debt, the better question is not simply who owes the most – but who is under the most pressure to pay it back.

RELATED: Africa and Caribbean trade potential could reach $1.65 billion annually by 2030: International Trade Centre (ITC)-Afreximbank report
From Guyana Government Partner To U.S.-Sanctioned Network: Opposition Demands Answers In The IMSAG Affair

By News Americas Now Staff Writer

News Americas, GEORGETOWN, Guyana, Tues. Nov. 10, 2026: In March 2021, the picture from Guyana was one of partnership, investment and opportunity. A news report published in the state-owned Guyana Chronicle announced a proposed US$35 million joint venture aimed at boosting Guyana’s maritime industry. Photographs showed Indian businessman Captain Suniel Kumar Sharma and associates alongside senior Guyanese officials as plans were promoted for a marine training institute, shipyard and dry dock, scholarships and hundreds of jobs. The venture was not presented as an outsider operating without government knowledge.

According to the article, Guyana’s Maritime Administration Department, MARAD, had entered into formal arrangements involving Sharma-linked entities. On February 4, 2021, MARAD Director General Captain Stephen Thomas signed an agreement delegating statutory certification services for Guyana-registered vessels. On March 3, MARAD and the Ministry of Public Works entered into a Memorandum of Understanding appointing Sharma’s Aryavart Corporation as an international technical and administrative representative of the Guyana Ships Registry under the name International Maritime Safety Agency of Guyana, IMSAG.

The March 2021 Chronicle report went even further, promoting plans for more than US$35 million in investment, a maritime training institute, shipyard and dry dock, 100 scholarships and more than 600 jobs for Guyanese. Opposition Member of Parliament Amanza Walton says the report also recorded commitments from Public Works Minister Bishop Juan Edghill, then Minister within the Ministry Deodat Indar, MARAD Director General Thomas and GO-Invest CEO Dr. Peter Ramsaroop to work with the venture.

FIVE YEARS LATER

Five years later, the story looks very different. On November 4, 2026, the U.S. Department of the Treasury sanctioned Sharma, his wife Jaspreet Preeti Shahid and several associated entities, accusing their network of operating fraudulent maritime registries and providing false flags and certifications to vessels transporting Iranian petroleum, including vessels linked to Iran’s military and its proxies.

Among the entities sanctioned was Aryavart Ship Management Private Limited. Treasury also sanctioned companies controlled by Shahid, including Alexarya Finserv Private Limited and Alexarya Media and Entertainment Private Limited.

THE IRONY

The following day, Guyana’s MARAD welcomed the U.S. action. MARAD described Sharma and Shahid as instrumental in managing a network that fraudulently represented vessels as registered in Guyana through IMSAG and said the government remained committed to preventing fraudulent use of the Guyana flag.

That response has now triggered questions from a political opposition party about how the same enterprise moved from an officially recognized relationship with Guyanese authorities to what the government now describes as a fraudulent operation.

WALTON: GOVERNMENT MUST EXPLAIN ITS ROLE

Opposition Member of Parliament Amanza Walton has accused the governing People’s Progressive Party/Civic, PPP/C, of hypocrisy over its response to the U.S. sanctions. In an opinion piece titled “From Red Carpet to Rogue Enterprise: The PPP Government must answer for its role in the IMSAG Affair,” Walton argues that the government cannot present itself solely as a defender of Guyana’s maritime registry without accounting for the formal relationship it previously established with Sharma and his companies.

Walton points specifically to the February and March 2021 agreements and the highly publicized investment plans that followed. “These are not my allegations,” Walton wrote, noting that details of the agreements were later referenced in correspondence from Guyana’s Attorney General to Sharma.

Her central question is straightforward: if the relationship later proved problematic, what due diligence was carried out before Sharma-linked entities were given authority connected to Guyana’s international ship registry? Walton is also asking who introduced Sharma to the Ministry of Public Works, who approved the arrangements and when officials first became aware of alleged misconduct.

FROM PARTNERSHIP TO TERMINATION

Guyana eventually severed the relationship. MARAD has said it terminated all arrangements with IMSAG on August 13, 2021. But that termination became widely visible months later after the cargo vessel Eolika, reportedly carrying illegal arms and ammunition, was detained in Senegal while purportedly operating under Guyana registration.

On January 20, 2022, MARAD said Eolika was not contained in Guyana’s local ships registry and that its documents were believed to have been issued by IMSAG. MARAD said it had severed all ties with the company several months earlier. Four days later, the Guyana government issued a much stronger statement declaring that it was “in no way connected or related” to IMSAG or its principals.

That statement acknowledged what it described as an “undertaking” with MARAD but said the relationship had been halted after fraudulent representations and illicit conduct were discovered. Walton argues that description understated the extent of the earlier official relationship because the Ministry of Public Works itself had been involved in the March 2021 Memorandum of Understanding.

A RELATIONSHIP THAT ONCE HAD OFFICIAL AUTHORITY

An investigation published by Bellingcat in February 2026 adds important context. The investigative outlet found that IMSAG was not always operating without Guyana’s authorization.

“Crucial to understanding how IMSAG has continued to operate as a fraudulent registry for so long is that it was once legitimate,” Bellingcat reported. Its investigation found that while the MoU was in effect, IMSAG served as Guyana’s international ship registry and used the imsag.org domain to register and flag vessels on Guyana’s behalf. Guyana later terminated the arrangement, but Bellingcat found evidence that certificates continued to be issued under the IMSAG name years afterward.

Bellingcat said it downloaded 230 vessel certificates covering 87 ships, including certificates issued as recently as December 2025 — long after Guyana withdrew its authorization.

Sharma has disputed allegations surrounding his current involvement. He previously told the Financial Times that the Guyana registry had been discontinued after authorities withdrew consent and later told Lloyd’s List that he had left the ship-registration business.

U.S. TREASURY: NETWORK SUPPORTED IRAN’S SHADOW FLEET

The November 2026 U.S. sanctions dramatically raised the stakes. Treasury accused Sharma and Shahid of building a network of false flagging authorities and maritime classification societies across multiple jurisdictions. The department said the network purported to represent countries ranging from Guyana to Eswatini and Laos and enabled vessels tied to Iran’s shadow fleet to evade international restrictions.

Treasury also cited the April 2026 seizure of the Majestic X, formerly the Phonix, which it said was falsely flying Guyana’s flag while carrying Iranian oil. MARAD, in welcoming the sanctions, said Guyana had consistently raised fraudulent registration at regional and international maritime forums and supported stronger international action against such schemes.

THE ACCOUNTABILITY QUESTIONS

The documentary record establishes two facts that now sit beside each other. In 2021, Guyanese authorities entered formal arrangements connected to Sharma and promoted significant investment plans involving his enterprise.

By 2022, the government had severed those arrangements and publicly denounced IMSAG. By 2026, U.S. authorities were sanctioning Sharma, Shahid and associated companies over an alleged global maritime fraud network, while the Guyana government welcomed the crackdown.

The unresolved issue is what happened between those points. When did Guyanese officials first discover problems with the operation?; What due diligence preceded the February and March 2021 agreements?; Why was the termination of the relationship not immediately announced publicly?; Who authorized Sharma-linked entities to represent Guyana internationally?; And what safeguards were put in place after that authorization was withdrawn?

Walton says those questions require more than a statement welcoming sanctions. For Guyana, the issue is no longer simply whether IMSAG later used the country’s flag without authorization. It is also how an enterprise once publicly embraced as a partner of the state obtained that authority in the first place — and whether the full story of that relationship has ever been disclosed.

RELATED: ‘Half Way To Hell’: Guyana Opposition Leader Azruddin Mohamed Details Life In Lusignan’s Building 5

Africa and Caribbean trade potential could reach $1.65 billion annually by 2030: International Trade Centre (ITC)-Afreximbank report
ST. JOHN’S, Antigua and Barbuda, Nov. 3, 2026 /PRNewswire/ — Annual trade in goods and services between Africa and the Caribbean could reach up to $1.65 billion by 2030, excluding mineral fuels, according to a new report launched today by the International Trade Centre (ITC) and African Export-Import Bank (Afreximbank) (www.Afreximbank.com) on the sidelines of the Commonwealth Heads of Government Meeting in Antigua and Barbuda.

The report, Reshaping Africa-Caribbean Trade: Opportunities for Economic Transformation (https://apo-opa.co/4eiz62u), finds that while Africa and the Caribbean share deep historical and cultural links, trade between the two regions continues to represent only a small share of each region’s overall trade, despite complementarities across sectors ranging from agribusiness and manufacturing to services and the creative economy.

A look at the numbers

The report finds that around 80% of Africa’s annual goods export potential to the Caribbean remains untapped, with are significant opportunities for export growth if trade and investment is actively promoted and facilitated.

Caribbean export potential lies in the services sector, reaching $481 million. The report identifies business opportunities across several priority sectors, including processed food and animal feed, chemicals, minerals and metals, apparel and textiles, leather and footwear, tourism, transport services and creative industries.

These findings – and more – are based on trade and export potential analysis, detailed sector assessments and a survey of 1,175 businesses and business support organizations across Africa and the Caribbean.

Tapping into priority sectors

ITC Executive Director Pamela Coke-Hamilton (https://apo-opa.co/3WHHZMU), in launching the report, said: ‘At a time of major shifts in global trade, countries need to strengthen regional ties and invest in value addition, to build resilience. We know the major trade opportunities between Africa and the Caribbean – and now we can focus on helping businesses take advantage of those opportunities through better market intelligence, improved logistics and greater access to finance.’

Commenting on the report, Denys Denya, Senior Executive Vice President at Afreximbank, said: ‘Africa and the Caribbean must transform a shared history into shared prosperity. With our CARICOM office in Barbados, about $1 billion in approved transactions and a $5 billion regional financing commitment, Afreximbank is advancing this vision through financing, deposit mobilization under CENDEP, business links through the annual Afri-Caribbean Trade and Investment Forum, local-currency payments through CAPSS and creative-industry collaboration through CANEX. This report offers a practical roadmap to turn untapped potential into bankable opportunities across agribusiness, manufacturing, tourism and the creative economy. Through targeted financing, stronger transport and logistics links and strategic partnerships, we can build a Global Africa connected by heritage, trade, investment and shared opportunity.’

The report finds that businesses continue to face significant challenges, including high transport costs, limited direct shipping links, regulatory barriers, limited access to finance and difficulties in identifying trusted commercial partners. It highlights that future economic cooperation should extend beyond traditional trade in goods, including through joint investment ventures, digital services, creative industries and tourism. It also calls for targeted action to improve market intelligence and business matchmaking; expand access to trade finance and payment solutions; strengthen transport and logistics connectivity; support sector-specific value chain development; improve regulatory cooperation and market access; and foster stronger partnerships among business support organizations.

Read the full report HERE (https://apo-opa.co/4exHBH9)

Distributed by APO Group on behalf of Afreximbank.

Follow ITC on:
X: https://apo-opa.co/4z3kD1Z
Facebook: https://apo-opa.co/4BICUnF
LinkedIn: https://apo-opa.co/4BDDaV3
Instagram: https://apo-opa.co/4iV8lDJ
Flickr: https://apo-opa.co/3Wny1Ad

Follow Afreximbank on:
X: https://apo-opa.co/3UbPNpx
Facebook: https://apo-opa.co/4z1pbFZ
LinkedIn: https://apo-opa.co/4yW1wXm
Instagram: https://apo-opa.co/47Z0Ntt

About the International Trade Centre:
The International Trade Centre is the joint agency of the World Trade Organization (https://apo-opa.co/4BMqF9K) and the United Nations (https://apo-opa.co/4zsjXUT). ITC assists small and medium-sized enterprises in developing and transition economies to become more competitive in global markets, thereby contributing to sustainable economic development within the frameworks of the Aid-for-Trade agenda and the United Nations’ Sustainable Development Goals.

For more information, visit www.InTraCen.org.

About Afreximbank:
African Export-Import Bank (Afreximbank) is a Pan-African multilateral financial institution mandated to finance and promote intra- and extra-African trade. For over 30 years, the Bank has been deploying innovative structures to deliver financing solutions that support the transformation of the structure of Africa’s trade, accelerating industrialisation and intra-regional trade, thereby boosting economic expansion in Africa. A strong supporter of the African Continental Free Trade Agreement (AfCFTA), Afreximbank has launched a Pan-African Payment and Settlement System (PAPSS) that was adopted by the African Union (AU) as the payment and settlement platform to underpin the implementation of the AfCFTA. Working with the AfCFTA Secretariat and the AU, the Bank has set up a $10 billion Adjustment Fund to support member countries effectively participate in the AfCFTA. At the end of December 2025, Afreximbank’s total assets and contingencies stood at over US$48.5 billion, and its shareholder funds amounted to US$8.4 billion. Afreximbank has investment grade ratings assigned by China Chengxin International Credit Rating Co., Ltd (CCXI) (AAA), GCR (A), Japan Credit Rating Agency (JCR) (A-), Moody’s (Baa2) and S&P Global Ratings (BBB+). The Bank is headquartered in Cairo, Egypt. Afreximbank has evolved into a group entity comprising the Bank, its equity impact fund subsidiary called the Fund for Export Development Africa (FEDA), and its insurance management subsidiary, AfrexInsure (together, “the Group”). The Bank is headquartered in Cairo, Egypt.

For more information, visit: www.Afreximbank.com

RELATED: Afreximbank Barbados Country Brief spotlights market’s economic resilience and reform-driven path for growth

Caribbean Passports Attract U.S.-Based Investors As EU Pressure Builds

By News Americas Now Business Editor

News Americas Now, MIAMI, FL, Fri. Oct. 30, 2026: U.S.-based investors are emerging as the largest source of prospective clients for Caribbean passports and citizenship-by-investment programs, even as five Eastern Caribbean nations face growing pressure from the European Union over the future of their passport-for-investment schemes.

New consultation data from international citizenship and residency advisory firm Immigrant Invest shows U.S.-based residents accounted for 16 percent of its Caribbean citizenship consultations between Jan. 1 and Oct. 15, 2026, making the United States the firm’s largest source market.

Across Antigua and Barbuda, Dominica, Grenada, St. Kitts and Nevis, and St. Lucia, U.S.-based clients ranked first overall, ahead of Nigeria, the United Arab Emirates and Türkiye. The strongest U.S.-based interest was recorded in St. Lucia, where 25 percent of consultations came from U.S.-based clients. St. Kitts and Nevis and Dominica each recorded 20 percent, Grenada 15 percent, while Antigua and Barbuda saw U.S.-based and Nigerian clients tied at 13 percent.

THE NUMBERS

The figures represent Immigrant Invest’s own consultation activity and should not be read as total application volumes across the Caribbean investment migration industry. The company defines an inquiry as a unique prospective client who held at least one consultation about a program.

U.S. CLIENTS LEAD CARIBBEAN INTEREST

Elena Ruda, co-founder and managing partner of Immigrant Invest, said Caribbean citizenship programs remain highly popular with U.S.-based clients, with particularly strong demand coming from Florida, followed by California, New York, Texas and Massachusetts. For many families, she said, the programs serve as both a backup residency or citizenship strategy and an investment decision.

“Most of our clients choose the real estate route, including shares in hotel and resort projects,” Ruda said. That property-linked demand matters for Caribbean economies because approved real estate investments are typically tied to hotels, resorts, villas and other tourism-related developments.

According to Immigrant Invest, minimum non-refundable government-fund contributions currently begin at US$200,000 in Dominica and rise to US$250,000 in St. Kitts and Nevis, while Antigua and Barbuda, Grenada and St. Lucia fall between those levels. Real estate thresholds are higher and vary by jurisdiction, with qualifying projects generally requiring investment in government-approved developments and minimum holding periods before resale.

EU PRESSURE CLOUDS THE MARKET

The demand is growing at the same time the European Union is increasing scrutiny of citizenship-by-investment programs. Under revised EU visa-suspension rules, operating an investor citizenship program can be considered grounds for suspending visa-free access to Europe’s Schengen Area. The European Commission has specifically identified Antigua and Barbuda, Dominica, Grenada, St. Kitts and Nevis, and St. Lucia in its monitoring of citizenship-by-investment schemes.

Letters sent by the Commission on June 25 asked the five governments to phase out their programs by June 1, 2028, while also strengthening vetting procedures and excluding applicants subject to EU restrictive measures. No Caribbean program has closed in response, and visa-free access to the Schengen Area has not been suspended. The June 2028 date is a requested phase-out deadline from the Commission, not an automatic date for the removal of visa-free travel privileges.

INVESTORS TAKE A WAIT-AND-SEE APPROACH

The regulatory uncertainty is already affecting investor behavior. Immigrant Invest said prospective clients across nationalities, including those based in the United States, have become more cautious since the June letters.

Many are now waiting for the European Commission’s next report and for responses from Caribbean governments before proceeding. The firm characterized the change as a pause for clarity rather than a collapse in demand. For Caribbean governments, the stakes extend beyond the investment migration sector itself.

Citizenship-by-investment programs have become important sources of government revenue, foreign investment and development financing in several Eastern Caribbean economies. At the same time, visa-free travel to Europe remains a valuable benefit for ordinary passport holders who have no connection to investment migration. Any future suspension of Schengen access would therefore affect both prospective investors and existing citizens.

REAL ESTATE, TOURISM AND CAPITAL FLOWS

The latest consultation figures also underline the broader economic role citizenship-by-investment programs can play in attracting foreign capital into tourism and real estate. Government-approved projects across the region include hotels, resorts, villas and other hospitality developments, creating a direct link between investment migration and the Caribbean tourism economy.

That creates both opportunity and risk. If U.S.-based interest continues to grow, Caribbean programs could remain a meaningful source of new capital.

But if EU pressure ultimately forces governments to close or substantially restructure their programs, the region could face a more difficult balancing act between protecting investment revenue, maintaining international travel access and preserving the credibility of its citizenship regimes. For now, demand from U.S.-based clients remains strong — but investors are watching Brussels closely.

RELATED: Why Investing in the Caribbean Is the Smartest Investment Move of 2026

US Pledges Over $340 Million In New Funding To The Caribbean – But Says Little About Deportations Or Boat Strikes

By News Americas Now Staff Writer

News Americas Now, NY, NY, Fri. Oct. 16, 2026: The United States announced more than $340 million in new funding commitments to the Caribbean on Wednesday at the opening of the U.S.-Caribbean Dialogue in Washington, as Deputy Secretary of State Christopher Landau laid out a sweeping set of economic and security pledges to a room of regional leaders led by CARICOM chairman and Saint Lucia Prime Minister Philip J. Pierre.

Calling the dialogue “overdue,” Landau said the Trump administration’s approach to the hemisphere rests on three pillars: economic investment in the region, ending what he called the “narco-terrorist threat,” and ending illegal immigration. He linked drug trafficking through the Caribbean directly to the more than 100,000 annual U.S. overdose deaths, and told the room the administration would not continue “business as usual” with the region.

“We’re taking actions accordingly. And we’d like to work with your countries to make sure that we’re all on the same page, at least in recognizing the common danger of this and seeing how we can try to address this scourge together,” he said.

NEW COMMITMENTS

The new commitments he announced include:

$61.5 million to launch ASPIRE – the America Strategic Partnership for Independent Regional Healthcare Excellence – aimed at building the region’s own healthcare workforce capacity.

$37 million in new Caribbean Basin Security Initiative (CBSI) programming to protect critical digital infrastructure and strengthen port security.

$55.5 million to strengthen regional law enforcement, including on illegal fishing, plus $11 million in Foreign Military Financing to build up Caribbean security forces.

$175.8 million for a Caribbean and Central America undersea cables program, intended to provide secure, high-speed connectivity across the region.

U.S.-Caribbean investment dialogue

Landau also announced a U.S.-Caribbean investment dialogue to launch next year, aimed at connecting Caribbean governments directly with American private-sector companies, and said the next CBSI security ministerial will convene in spring 2027.

Pierre, delivering brief remarks as CARICOM chair, welcomed the dialogue and named the region’s priorities as affordable energy, investment, safer communities, and reliable disaster response. He said Haiti “must remain central” to the partnership, welcomed the extension of the UN-backed Gang Suppression Force mandate there, and said credible elections are essential to restoring the country’s stability.

On the issue most on the minds of Caribbean nationals right now, Pierre offered a single, carefully diplomatic sentence: the dialogue, he said, “must make room for immigration and migration matters, with profound implications for our communities and our people-to-people ties.” It was the closest either leader came, in their prepared remarks, to directly addressing deportations or the U.S. military’s ongoing boat-strike campaign in the region.

“Let us connect political dialogue with sustained technical engagements, identify priorities, and establish clear arrangements for follow-up between governments and the private sector,” he added. “The CARICOM Secretariat will help coordinate the community’s technical work alongside our national authorities and regional institutions. CARICOM comes to this table ready to listen, ready to engage, and ready to build a partnership that delivers mutual benefit, with respect for our sovereignty and our shared aspirations.”

Neither Landau’s nor Pierre’s remarks, as delivered, referenced the boat strikes against alleged drug-trafficking vessels – which have killed at least 238 people since September 2025, including confirmed Caribbean nationals – or the deportation agreements several Caribbean nations, including Jamaica, Guyana, and Saint Lucia, have signed with Washington in recent months. Both issues have generated significant controversy and political friction in the region, even as officials on both sides described Wednesday’s funding announcements as evidence of a strengthening partnership.

RELATED: Caribbean Leaders Talk “Partnership” With The US Today While Absorbing Its Deportees And Boat-Strikes

Guyana Is Sitting On A $19.6 Billion Exxon Audit It Still Won’t Release

By News Americas Now Business Editor

News Americas Now, NY, NY, Fri. Oct. 16, 2026: As Guyana’s oil economy posts some of the fastest growth rates in the world, the government is holding back a US$19.6 billion audit of ExxonMobil’s spending that it has possessed since May 2025 – the largest and most consequential of three outstanding cost-oil audits the International Monetary Fund flagged this week as a governance risk.

The IMF’s 2026 Article IV consultation, released last week, praised Guyana’s economic trajectory – 19.3% real GDP growth in 2025, projected to hit 22.3% in 2026 – while explicitly calling on the government to resolve its backlog of unpublished oil audits and strengthen transparency around how ExxonMobil’s costs are being verified.

“Priorities include resolving outstanding cost-oil audits, improving the timeliness of public enterprise and agency accounts, further strengthening audit capacity, especially in the oil and gas sector, and ensuring consistent compliance with the procurement framework as public spending expands.,” the IMF stated. “Efforts to strengthen AML/CFT and anti-corruption frameworks should continue, including by strengthening the Integrity Commission and the asset declaration regime.’

THE PATTERN

The pattern spans three separate audits. The first, covering 1999–2017, flagged US$214 million in disputed costs more than five years ago; that dispute has only now reached the International Chamber of Commerce, which is working to appoint a sole expert to resolve it, Natural Resources Minister Vickram Bharrat confirmed, with no timeline yet set. A second audit, for 2018–2020, found an additional US$65 million incorrectly charged to the country. But it’s the third audit — covering US$19.6 billion in Exxon costs, by far the largest sum in question — that the government has sat on since last May without releasing it or addressing what the auditors found.

The IMF’s broader message was pointed: durable prosperity from Guyana’s oil wealth depends on governance keeping pace with growth, not just the growth itself. The Fund also pushed Guyana to tighten public procurement compliance, reinforce anti-corruption safeguards, and move away from broad consumer subsidies toward targeted assistance — all while warning that the country’s fiscal deficit is set to widen from 5.5% of GDP to 6.4% in 2026 before improving in 2027.

With Guyana’s Natural Resource Fund now holding roughly US$3.3 billion and the country posting some of the highest reserves and lowest debt ratios in the Western Hemisphere, the open question the IMF is effectively putting on record is whether the government intends to make the full scale of disputed Exxon costs public —- or continue managing the country’s oil wealth with its largest audit kept out of view.

RELATED: Guyana Record Oil Profit Share Could Be Temporary – Here’s Why

Guyana Record Oil Profit Share Could Be Temporary – Here’s Why

By News Americas Now Business Editor

News Americas Now, GEORGETOWN, Guyana, Thurs. Oct. 15, 2026: Guyana collected close to US$1 billion in oil revenue in September for the second straight month, but the country’s newly elevated profit share from the Stabroek Block carries a built-in vulnerability that could erase those gains if the government isn’t careful about how it approves ExxonMobil’s next projects.

The Natural Resource Fund took in US$768 million in profit oil in September, following a US$778 million collection in August that included a signing-bonus payment. Guyana is now capturing 39.8% of Stabroek Block profits plus a 2% royalty – a dramatic rise from the 12.5% profit share the country held for years under its original 2016 Production Sharing Agreement, which allowed ExxonMobil to recover 75% of monthly production before any profit-sharing began. That cost-recovery phase ended because Exxon has now repaid its full US$55 billion investment in Guyana’s offshore fields.

THE MATH

But the math that got Guyana to 39.8% can run in reverse. ExxonMobil is currently pursuing an eighth and ninth development project in the Stabroek Block. Each new project adds fresh costs to the cost-recovery bank — and if the government approves them under the existing financial terms, Guyana’s profit share could slide back toward the original 12.5%, effectively giving away the gains the country has only just started collecting.

President Irfaan Ali has said the government will seek expert advice on how future Exxon projects are financed, including whether Guyana should take a direct investment stake in upcoming developments to lock in a larger, durable share of returns rather than relying on the current cost-recovery structure. How that question gets answered – not this month’s deposit figure – will determine whether Guyana’s current oil windfall is the new normal or a high-water mark.

Four projects are currently producing roughly 900,000 barrels per day in the Stabroek Block. A fifth, Uaru, is expected to push the country past one million barrels per day before the end of 2026.

RELATED: Guyana – Oil Exports Top $15 Billion In Just Six Months

Afreximbank Barbados Country Brief spotlights market’s economic resilience and reform-driven path for growth

CAIRO, Oct. 12, 2026 /PRNewswire-HISPANIC PR WIRE/ — African Export-Import Bank (Afreximbank) (www.Afreximbank.com) has released its latest Barbados Country brief, offering a comprehensive and timely analysis of the island nation’s macroeconomic outlook. The brief explores key regional and international trade dynamics, financial sector developments and debt sustainability trends.

The brief highlights that Barbados has exhibited resilient growth following the Covid-19 pandemic, with GDP growth averaging 5.6% between 2021 and 2026, driven by a robust resurgence in tourism. Growth is forecast at 1.9% in 2026 and 2.3% in 2027, supported by resilient tourism inflows, a strong pipeline of investment projects and targeted government support for households and businesses.

Central to this transformation is Barbados’ IMF-backed Barbados Economic Recovery and Transformation (BERT) programme. The brief notes that the original BERT programme concluded successfully in 2025, with the IMF Executive Board approving a new 36-month precautionary Stand-By Arrangement of USD257 million in June 2026 to support the next phase of structural reform. This reflects the international community’s confidence in Barbados’ policy track record and the market’s commitment to building a resilient and diversified economy.

This brief edition also explores the high-income island nation’s impressive fiscal consolidation. Public debt has declined from 104.1% of GDP at end-FY2023/24 to 96% of GDP at end-March 2026, backed by a primary fiscal surplus of 4.2% of GDP in FY2025/26. The government’s medium-term framework targets sustained primary surpluses of 3.5% of GDP, placing public debt on a firm trajectory towards the 60% of GDP anchor by FY2035/36. The IMF assesses the overall risk of sovereign stress as moderate, reflecting Barbados’ strong and consistent policy track record.

On trade, the brief points to a steadily strengthening external position. Total goods and services trade grew from USD4.1 billion in 2018 to USD5.5 billion in 2024, with further expansion to USD6.3 billion projected in 2026. Barbados’ services balance remains a key pillar of strength, underpinned by tourism inflows that grew 3.7% in the first quarter of 2026, bolstered by a 30% year-on-year jump in cruise ship arrivals.

The brief further highlights developments within Barbados’ deep and diversified financial sector. In June 2026, the Central Bank of Barbados launched BiMPay, a national instant payment system enabling round-the-clock settlements and broadening financial inclusion. This represents the latest in a series of measures to strengthen the efficiency and resilience of the country’s financial infrastructure.

Commenting on the brief, Dr Yemi Kale, Afreximbank’s Group Chief Economist and Managing Director, Research and Trade Intelligence, noted: “The findings highlight Barbados as a dynamic, reform-driven economy whose resilient fundamentals, stable governance and deepening regional ties position it as an increasingly compelling partner for trade finance and development cooperation across the Caribbean.”

Read more about the Afreximbank Country Brief on Barbados https://apo-opa.co/47NXZPE

Distributed by APO Group on behalf of Afreximbank.

Follow Afreximbank on:
X: https://apo-opa.co/4f1yTjE
Facebook: https://apo-opa.co/3R38D0b
LinkedIn: https://apo-opa.co/4f9bdKd
Instagram: https://apo-opa.co/44hnKq8

About Afreximbank:
African Export-Import Bank (Afreximbank) is a Pan-African multilateral financial institution mandated to finance and promote intra- and extra-African trade. For over 30 years, the Bank has been deploying innovative structures to deliver financing solutions that support the transformation of the structure of Africa’s trade, accelerating industrialisation and intra-regional trade, thereby boosting economic expansion in Africa. A stalwart supporter of the African Continental Free Trade Agreement (AfCFTA), Afreximbank has launched a Pan-African Payment and Settlement System (PAPSS) that was adopted by the African Union (AU) as the payment and settlement platform to underpin the implementation of the AfCFTA. Working with the AfCFTA Secretariat and the AU, the Bank has set up a US$10 billion Adjustment Fund to support countries effectively participating in the AfCFTA. At the end of December 2025, Afreximbank’s total assets and contingencies stood at over US$48.5 billion, and its shareholder funds amounted to US$8.4 billion. Afreximbank has investment grade ratings assigned by China Chengxin International Credit Rating Co., Ltd (CCXI) (AAA), GCR (A), Japan Credit Rating Agency (JCR) (A-), Moody’s (Baa2) and S&P Global Ratings (BBB+). The Bank is headquartered in Cairo, Egypt. Afreximbank has evolved into a group entity comprising the Bank, its equity impact fund subsidiary called the Fund for Export Development Africa (FEDA), and its insurance management subsidiary, AfrexInsure (together, “the Group”). The Bank is headquartered in Cairo, Egypt.

For more information, visit: www.Afreximbank.com

YOU MAY ALSO LIKE: Guyana – Oil Exports Top $15 Billion In Just Six Months

Guyana – Oil Exports Top $15 Billion In Just Six Months

By News Americas Now Business Editor

News Americas Now, GEORGETOWN, Guyana, Weds. Oct. 7, 2026:  Guyana’s petroleum sector delivered a record first half of 2026, with crude oil exports surpassing US$15 billion and total export earnings jumping 76.4 percent to US$16.2 billion, according to the Guyana Mid-Year Report.

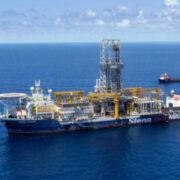
The surge was driven by a 40 percent increase in export volumes combined with a 28.9 percent rise in crude prices. Daily production nearly doubled, climbing from roughly 639,000 barrels per day to approximately 902,000 barrels per day, as four Floating Production, Storage and Offloading (FPSO) vessels operated simultaneously in the offshore Stabroek Block.

The One Guyana FPSO, which came online in August 2025, ramped up output through the first half of the year, and a fifth vessel, the Errea Wittu, is expected to begin production by late 2026 – a signal that Guyana’s output growth is far from finished.

The windfall is reshaping the national economy. Real GDP expanded an estimated 33.3 percent in the first half of 2026, and the oil and gas sector alone is projected to grow 24.2 percent for the full year. The non-oil economy also posted solid, if more modest, growth of 10.1 percent, suggesting the boom is beginning to spread beyond the petroleum sector.

Full-year petroleum revenues are now projected at US$6.5 billion, a 136.8 percent increase over initial budget projections – underscoring how quickly Guyana’s oil wealth has outpaced even government forecasts.

For the Guyanese diaspora, the numbers represent more than fiscal headlines. They mark a continued, rapid transformation of a country that only a decade ago had no oil production at all, and they raise the stakes for how that wealth is managed, invested, and shared in the years ahead.

RELATED: Guyana – Oil Wealth Fund Surges Past $4.29 Billion – Here’s Where The Money Is Going

Guyana – Oil Wealth Fund Surges Past $4.29 Billion – Here’s Where The Money Is Going

By News Americas Now Business Editor

News Americas Now, GEORGETOWN, Guyana, Tues. Oct. 6, 2206: As its oil exports hit record highs, the Natural Resource Fund of Guyana – the sovereign wealth fund set up to manage petroleum earnings – has swelled to US$4.2942 billion as of the end of June 2026, according to the government’s Mid-Year Report.

The fund’s growth is being fed by a rapid rise in profit-oil revenue. The government is projected to earn US$5.9725 billion from the sale of Guyana’s share of profit oil for the year, along with an additional US$508.1 million in royalties – pushing full-year petroleum revenue projections to US$6.5 billion, well above original budget estimates.

Unlike the export and production figures that have dominated headlines, the Natural Resource Fund is the mechanism meant to determine how lasting Guyana’s oil boom will be. Money deposited into the fund is earmarked, under Guyana’s own legal framework, to support national development spending – infrastructure, public services, and long-term investment – rather than being spent directly as it comes in.

That structure has put Guyana in a similar position to other resource-rich nations that have had to balance fast-moving oil wealth against the slower, harder work of building durable institutions around it. With four FPSOs already producing in the Stabroek Block and a fifth expected online by late 2026, the fund’s balance is likely to keep climbing just as quickly as the export figures have.

For Guyanese at home and in the diaspora, the fund’s growth raises a pointed question that will shape the next phase of the country’s transformation: not simply how much oil money is coming in, but how visibly and effectively it reaches roads, hospitals, schools and the everyday cost of living.

RELATED: The US$55 Billion Cost-Recovery Milestone: Bank Of Guyana Missing Details